
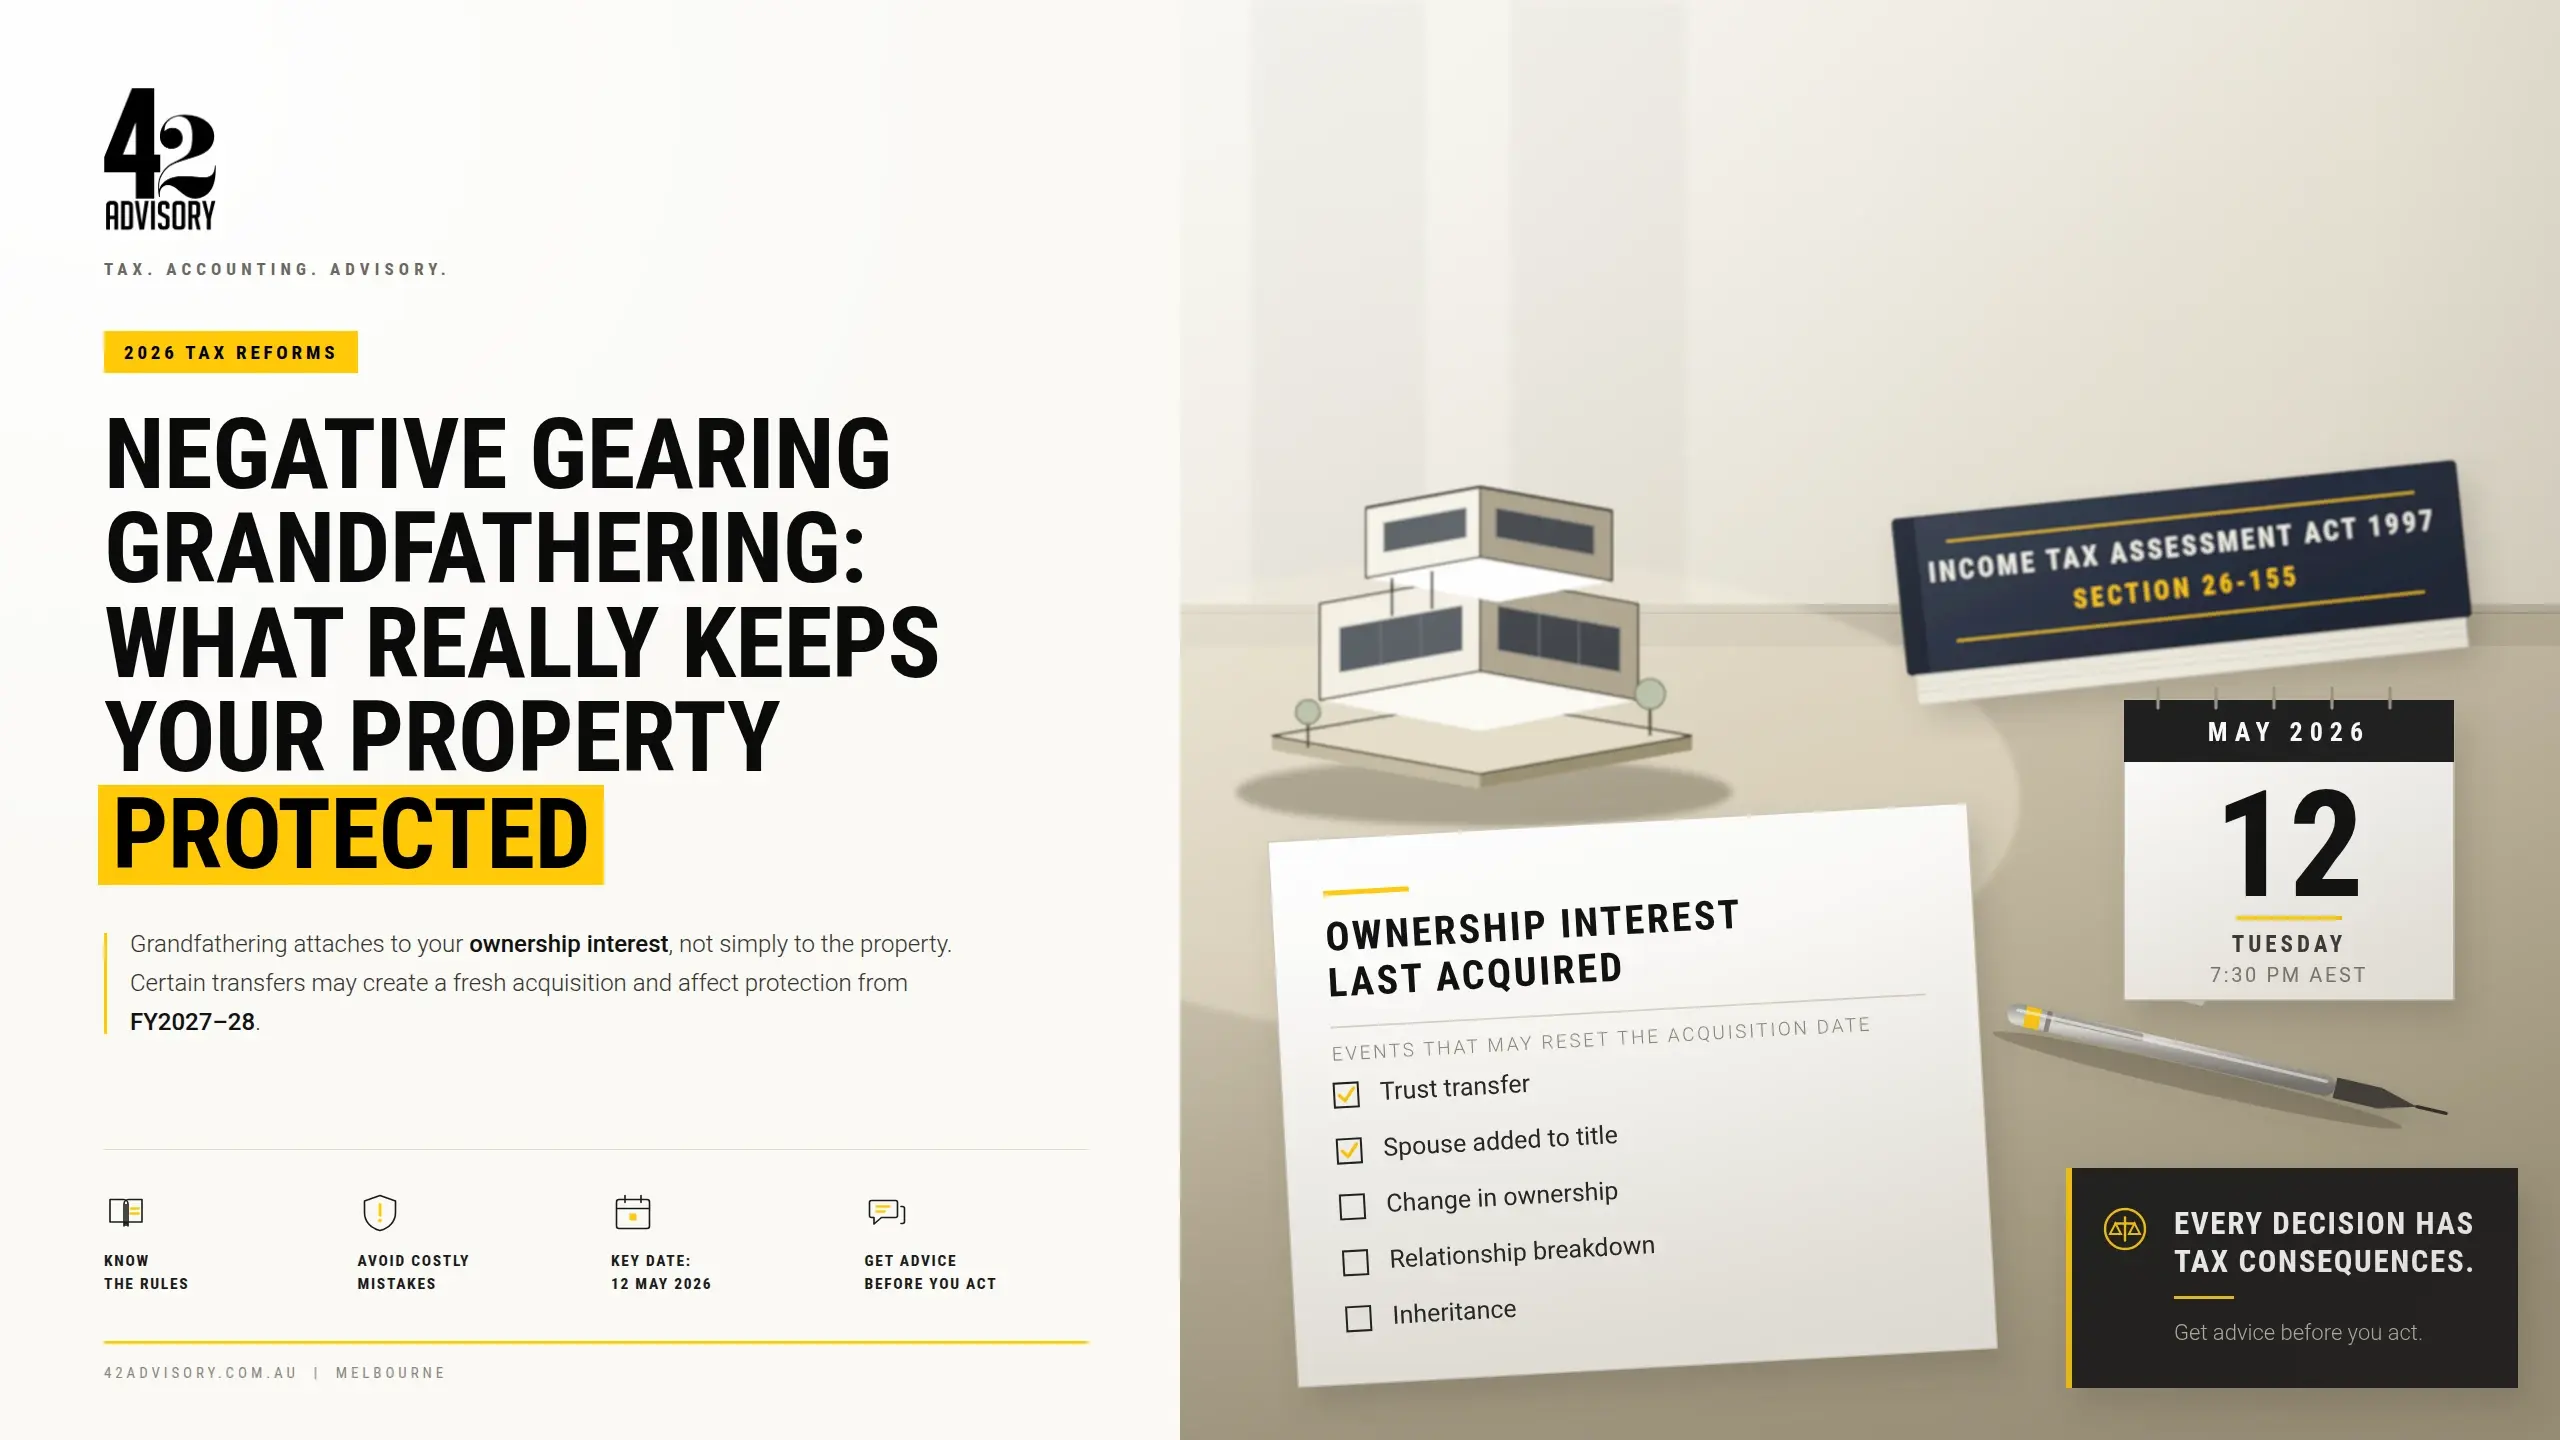
Negative gearing grandfathering attaches to your ownership interest, not to the property. From the 2027-28 income year, losses on residential property interests acquired after 7.30pm AEST on 12 May 2026 are quarantined. Transfers to a trust or company, adding a spouse to title and changing ownership proportions all create a fresh acquisition and break the concession. Death and relationship breakdown do too under the Act as enacted, though a Treasury draft released on 3 August 2026 would preserve both. That draft is not law.
- Enacted. The Treasury Laws Amendment (Tax Reform No. 1) Act 2026 received Royal Assent on 26 June 2026. Section 26-155 quarantines residential rental losses from the 2027-28 income year, and interests last acquired before 7.30pm AEST on 12 May 2026 are exempt.
- Draft only. Treasury released a second tranche of exposure draft legislation on 3 August 2026, with consultation closing on 21 August 2026. It would preserve grandfathering where an interest passes to a surviving spouse, to a surviving co-owner, or under a formal relationship breakdown order or agreement. It had not been introduced to Parliament as at 22 September 2026.
- No ATO guidance. The ATO's new legislation page was last updated on 29 June 2026 and does not deal with transfers, death or separation.
Grandfathering is the most reassuring word in the 2026 tax reforms. It is also the most misunderstood. Investors are being told that a property held before Budget night is protected "for as long as you own it", and on a plain reading of the law that is only half true. The protection attaches to your ownership interest, and ownership interests change hands more often than people think: restructures, separations, deaths, title changes between spouses.
The Treasury Laws Amendment (Tax Reform No. 1) Act 2026 received Royal Assent on 26 June 2026. Its negative gearing rules commence in the 2027-28 income year. That leaves a window in which many investors will restructure to manage the separate CGT changes, and some of those restructures will quietly destroy grandfathering they assumed was permanent. Treasury has since acknowledged part of the problem: the Tranche 2 consultation opened on 3 August 2026 with draft provisions that would keep the concession alive on death and on relationship breakdown. Nothing has been fixed for transfers to trusts and companies, and the draft itself is not law. This article explains how the exemption works, which transactions break it, what the draft would change, and why the usual CGT rollovers do not save you.
Does Grandfathering Apply to Negative Gearing?
Yes. Residential property interests last acquired before 7.30pm AEST on 12 May 2026 are exempt from the new negative gearing restrictions, which apply from the 2027-28 income year. Losses on those grandfathered interests remain deductible against salary and other income under the existing rules.
The new rule sits in section 26-155 of the Income Tax Assessment Act 1997. Where deductions relating to residential dwellings exceed the assessable income from them in a year, the excess is denied, quarantined, and carried forward. Quarantined amounts can only be used against future net residential rental income or gains on residential dwellings, and the Budget factsheet confirms they cannot shelter salary or business income.
The exemptions are set out in the Parliamentary Bills Digest: interests acquired before Budget night, eligible new residential dwellings, dwellings covered by ministerial determination (such as affordable housing), and property held by complying superannuation funds or widely held unit trusts. For most individual investors, the pre-Budget exemption is the one doing the work, which is why understanding its precise wording matters so much.
What Does "Last Acquired" Mean for Your Property?
The exemption applies to an ownership interest in a residential dwelling that the taxpayer last acquired before 7.30pm AEST on 12 May 2026. It is a test about the person and their interest, not the property. If the interest is re-acquired after that time, the grandfathering does not follow it.
This is the detail almost every summary skips. The word "acquired" would have been generous: hold the property from before Budget night and you are protected. The legislation instead says "last acquired". Every time an ownership interest changes hands, the recipient acquires it afresh, and the clock resets to that date. A property the family has held since 2005 can lose its protection through a single transfer document, because the person now holding it acquired their interest after the cut-off.
The ATO's new legislation guidance confirms the measures and the commencement date, but it was last updated on 29 June 2026 and says nothing about partial interests or transfers. Until it does, our view is that investors should treat any change of ownership interest as a potential grandfathering event and get advice before signing, not after. This is exactly the kind of question we model in our property tax advisory work: the decision that cannot be undone deserves the analysis before it is made.
Which Transactions Break Negative Gearing Grandfathering?
Transfers to a trust or company, adding a spouse to title and changing ownership proportions create a fresh acquisition and break grandfathering on the interest transferred. Death and relationship breakdown also break it under the Act as enacted, although draft legislation released on 3 August 2026 would preserve both. Holding, refinancing and renovating do not.
There are now two positions to hold in mind: the law as it stands today, and the law as the Tranche 2 draft would leave it. The table below sets out both.
| Transaction | Under the Act as enacted | If the Tranche 2 draft becomes law |
|---|---|---|
| Continue to hold as-is | Retained | No change |
| Refinance the loan | Retained | No change |
| Renovate the property | Retained | No change |
| Transfer to a family trust | Lost on the interest transferred | No relief proposed |
| Transfer to a company | Lost | No relief proposed |
| Add a spouse to title | Lost on the interest the spouse acquires | No relief proposed |
| Change ownership proportions | Lost on the increased portion only | No relief proposed |
| Interest passes to a surviving spouse on death | Lost, as the survivor acquires at the date of death | Preserved under proposed section 26-156 |
| Interest passes to a surviving co-owner who is not a spouse | Lost | Preserved under proposed section 26-157 |
| Property inherited by a child or other person who was not a co-owner | Lost | Not covered by the draft |
| Relationship breakdown transfer under a court order or binding financial agreement | Lost on the transferred interest, despite the CGT rollover | Preserved under proposed section 26-158 |
| Informal transfer on separation, outside a court order or agreement | Lost | Not covered by the draft |
Three points follow from that table. The commercial restructures are untouched: a transfer to a trust or a company breaks grandfathering today and would still break it under the draft, and Treasury has said only that a restructure rollover is among the matters still to be consulted on. The relief that has been drafted is narrow, turning on a spouse, an existing co-ownership, or a formal family law instrument. And none of it is law, so a transfer signed this month is governed by section 26-155 as enacted, whatever the draft eventually says.
Do the CGT Rollovers Preserve Grandfathering?
No. The marriage breakdown rollover and the deceased estate rules operate only within the capital gains tax provisions. They preserve cost base and defer gains, but the negative gearing test in section 26-155 is a deduction rule that asks when the taxpayer last acquired the interest. Draft legislation would fix this separately, not through the rollovers.
The confusion is understandable. When a property transfers between spouses under a court order or binding financial agreement, the automatic marriage breakdown rollover in Subdivision 126-A disregards the capital gain and hands the cost base to the receiving spouse. It feels as though nothing has changed. But the rollover lives entirely inside the CGT provisions. Section 26-155 sits in Division 26, among the deduction rules, and its test is the acquisition date of the person now claiming the deduction. The receiving spouse acquired their interest at the transfer date. If that is after 12 May 2026, the interest is not grandfathered, even though the CGT position rolled over perfectly.
Death works the same way, and here a common error in circulation needs correcting. Several published explainers claim that inherited property keeps the deceased's acquisition date. It does not. Section 128-15(2) of the ITAA 1997 deems the beneficiary or legal personal representative to have acquired the asset on the day the person died. What carries across is the cost base under the separate cost base rules, which is a different thing entirely. On the Act as enacted, a death after 12 May 2026 gives the recipient a post-Budget acquisition date, and the grandfathering goes with it.
Treasury has drafted a fix, and it works by going around the rollovers rather than through them. The Tranche 2 exposure draft inserts proposed sections 26-156, 26-157 and 26-158. Each says that where the transferor acquired the interest before the Budget night cut-off, the recipient is taken to have acquired it at that earlier time, and the death timing rule in section 128-15(2) is disregarded. Section 26-156 covers a surviving spouse taking as joint tenant or beneficiary, section 26-157 a surviving co-owner who is not a spouse, and section 26-158 a transfer under an order, agreement or award of the kind listed in paragraphs 126-5(1)(a) to (f). The gaps matter as much as the coverage. A child who inherits a property their parent owned alone sits outside all three, as does a separating couple who transfer title informally rather than under a family law instrument. Estate plans and settlement drafting built around loss-making rental properties should be reviewed on that basis, alongside broader tax planning for the family group.
A Worked Example: One Family, Two Tax Personalities
In our experience working with Melbourne property investors, the risk rarely arrives as a tax question. It arrives as an asset protection question, an estate question, or a separation. Consider an investor with two established residential units, both negatively geared:
- Unit 1, acquired in 2014. Net rental loss of $8,000 in 2027-28. Grandfathered.
- Unit 2, acquired in August 2026. Net rental loss of $12,000 in 2027-28. Not grandfathered.
In 2027-28, the $8,000 loss on Unit 1 deducts against salary as it always has. The $12,000 loss on Unit 2 is caught by section 26-155. It can only offset net income from other residential property, and Unit 1 made a loss, so there is nothing to offset. The full $12,000 is quarantined and carried forward. It cannot be added to the property's cost base either: the Act inserts specific provisions, sections 110-38(8A) and 110-55(9JA), to prevent exactly that. The quarantined amount waits for future residential rental profits or a residential capital gain.
Geared investors should also remember a separate, current-year cost that has nothing to do with the 2027 changes: total net investment losses are added back when working out income for Medicare levy surcharge purposes. A negatively geared portfolio can push an investor over the surcharge threshold even where taxable income sits below it. We explain the thresholds, rates and family rules in our guide to the Medicare levy surcharge.
Now suppose that in 2029, on asset protection advice, the investor transfers Unit 1 into a family trust. The trust acquires the interest in 2029, well after Budget night. From that point, Unit 1's losses inside the trust are quarantined too. A routine restructure has converted the portfolio from half-protected to fully caught, and no part of the Tranche 2 draft would help, because it deals with death and relationship breakdown rather than restructures. The stamp duty and CGT costs of the transfer would have been modelled as a matter of course; the grandfathering cost is the one that gets missed.
Restructuring before 1 July 2027?
We model every transfer across both the CGT reforms and the negative gearing rules before you sign anything, so a fix for one problem does not create a bigger one.
Contact UsShould You Restructure Before 1 July 2027?
Not without modelling both regimes together. The CGT reforms commencing 1 July 2027 create pressure to restructure holdings, but restructures involving residential property can permanently break negative gearing grandfathering on the interests transferred. Anti-avoidance rules also apply to arrangements driven mainly by tax outcomes.
The same Act rebuilds the CGT system: the second reading speech confirms the 50% discount is replaced with cost base indexation and a 30% minimum rate on gains accruing from 1 July 2027, with a deemed disposal and market value reset at 30 June 2027. We covered the small business side of these changes, including the active asset reduction turnover threshold rising from $2 million to $10 million, in our post on the 2026 CGT reform carve-outs.
That combination pushes investors toward restructuring in the window before commencement, and the two measures pull in opposite directions: the transactions that reposition assets for the CGT changes are the very transactions that break negative gearing grandfathering. There is a further constraint. Part IVA, the general anti-avoidance rule, can apply to schemes entered into for the dominant purpose of obtaining a tax benefit. A restructure needs genuine commercial drivers, documented at the time, and it needs numbers run across stamp duty, CGT, land tax, and now section 26-155. The Government's tax reform page flags further consultation to come, including on a restructure rollover, so acting early on incomplete rules carries its own risk. Investors holding property through super should also note the separate changes to SMSF borrowing, which our SMSF accountants can walk through, and individual owners should factor the changes into personal tax planning for 2027-28. For portfolio-level decisions, 3-way forecasting shows the cash flow effect of quarantined losses before they arrive. Our guide to common ATO property tax traps covers the compliance side.
Key Takeaways
| Takeaway | What to do this week |
|---|---|
| Grandfathering follows the interest, not the property | List every residential interest and its acquisition date against 12 May 2026 |
| Trust and company transfers break it, with no fix proposed | Pause any planned restructure of a grandfathered property until it is modelled |
| The death and separation fix is draft only, and narrow | Check whether your facts fit a surviving spouse, a surviving co-owner or a formal family law instrument |
| CGT rollovers do not reach the deduction test | Review estate plans and any separation settlements involving rental property |
| Quarantined losses cannot go to cost base | Forecast 2027-28 cash flow assuming caught losses give no refund |
| The rules are still moving | Get advice on your facts before acting; do not rely on general summaries or on draft law |
Check your grandfathering position before you sign
Book a meeting and we will map each ownership interest against the new rules, so you know exactly what a transfer would cost before it happens.
Book a MeetingDisclaimer: The information provided in this article is general in nature and does not constitute specific tax, legal, or financial advice. It states the position as at 22 September 2026. The negative gearing and CGT measures discussed commence from the 2027-28 income year, the sections 26-156 to 26-158 described here are exposure draft provisions that have not been introduced to Parliament and may change or not proceed, and several implementation details remain subject to ministerial determination and ATO guidance. Property transfers also involve legal and stamp duty considerations requiring advice from a solicitor, and family law settlements require advice from a family lawyer. We recommend seeking professional advice tailored to your individual circumstances. 42 Advisory is a CPA firm and Registered Tax Agent.
Frequently Asked Questions
Does grandfathering apply to negative gearing?
Yes. Interests in residential dwellings last acquired before 7.30pm AEST on 12 May 2026 are exempt from the new loss quarantine rules that apply from the 2027-28 income year. Losses on those interests remain deductible against other income under the existing negative gearing treatment.
What is the cut off date for grandfathering?
7.30pm AEST on 12 May 2026, which was Budget night. The test is when the taxpayer last acquired their ownership interest in the residential dwelling. Interests acquired at or after that time are subject to the new rules from 1 July 2027.
Who is exempt from negative gearing changes?
Interests acquired before Budget night, eligible new residential dwellings, dwellings covered by ministerial determination such as affordable housing, complying superannuation funds, and widely held unit trusts. Losses relating to fringe benefits are also excluded from the quarantine.
When do negative gearing changes come into effect?
From the 2027-28 income year, which starts on 1 July 2027. The legislation received Royal Assent on 26 June 2026, so the rules are law now, but the first year in which losses can be quarantined is 2027-28.
Is a property inherited after Budget night still grandfathered?
It depends on who inherits, and the answer may change. Under the Act as enacted, no: section 128-15(2) deems the recipient to acquire the asset on the date of death, which is after the cut-off. Treasury's exposure draft of 3 August 2026 would preserve grandfathering for a surviving spouse and a surviving co-owner, but not for a child inheriting a property their parent owned alone. That draft is not law.
What happens to grandfathering in a divorce or separation settlement?
Under the current law the receiving spouse acquires the interest at the transfer date and loses grandfathering, because the Subdivision 126-A rollover only addresses capital gains. Proposed section 26-158 would preserve it where the transfer is made under an order, agreement or award of a kind listed in paragraphs 126-5(1)(a) to (f). Informal transfers would fall outside that relief.
Does moving a property into a family trust keep negative gearing grandfathering?
No. The trust acquires the ownership interest on the transfer date, so an interest moved into a trust after 7.30pm AEST on 12 May 2026 is not grandfathered. No relief is proposed for restructures in the draft legislation released on 3 August 2026, and the Government has only flagged a possible restructure rollover for later consultation.
What does grandfathered mean in CGT?
In the 2026 reforms it usually refers to gains accrued before 1 July 2027, which keep access to the 50% discount through a deemed market value disposal at 30 June 2027. That CGT transitional treatment is separate from negative gearing grandfathering, which turns on when an ownership interest was last acquired.
Considering a transfer or change of title?
Sergiy Kucherenko
Sergiy Kucherenko is the founder and director of 42 Advisory and a member of CPA Australia. He has spent his career in public practice, working with business owners on tax, structuring and the practical problems that come with running a growing company. Before accounting, Sergiy trained as an engineer and studied computer science. The habit of building systems stuck. It is why the practice runs cloud-first and heavily automated, with Xero at the centre rather than paper files, and why he is comfortable acting for clients whose businesses are technical, software companies in particular. His client work covers medical technology, telecommunications, SaaS, construction and trades, and healthcare, including general practice and dental groups. Some clients come to him at incorporation; others when they are restructuring, acquiring or preparing to sell. The areas he knows best are service trust arrangements for medical practices, revenue recognition for SaaS businesses, and cash flow management in construction.